Real Estate · Offices
Suntec REIT Pivots to Singapore as Three Australian Assets Head to Market
Strategic shift follows portfolio review by new sponsor Tang Organisation, targets sub-40 per cent leverage and improved capital flexibility
KEY TAKEAWAYS
- ·Suntec REIT will sell three Australian office buildings at 177 Pacific Highway, 21 Harris Street and 477 Collins Street, aiming to reduce aggregate leverage below 40 per cent.
- ·The divestments follow a strategic review by new sponsor Tang Organisation and seek to offset earnings drag from Australia's 4.35 per cent benchmark interest rate.
- ·Singapore assets contribute 74 per cent of income for the S$12.2 billion trust, which reported a 24.8 per cent rise in first-half distribution per unit to S$0.03936.
Portfolio Realignment Under New Ownership
Suntec Real Estate Investment Trust has outlined plans to concentrate expansion in Singapore while trimming overseas holdings, beginning with the disposal of three Australian office properties. The real estate investment trust disclosed on 21 September that it intends to sell 177 Pacific Highway, 21 Harris Street and 477 Collins Street, citing favourable market conditions and sustained buyer interest in Australia's capital markets.
The decision follows a strategic portfolio review initiated in March by Tang Organisation, which assumed sponsorship after acquiring ESR Asset Management earlier this year. That review aimed to lift portfolio performance and sharpen capital efficiency across the trust's holdings.
Chong Kee Hiong, chief executive of the REIT's manager, said the divestments are expected to push aggregate leverage below 40 per cent, creating headroom for acquisitions, unit buybacks or distributions. Suntec REIT manages S$12.2 billion in total assets, comprising three properties in Singapore, four in Australia and two in the United Kingdom. Singapore assets contribute approximately 74 per cent of income, with Australia accounting for 15 per cent and the UK 11 per cent.
Rate Environment and Earnings Drag
The Australian sales also address earnings pressure from elevated interest rates in that market. Australia's benchmark rate stands at 4.35 per cent, materially higher than Singapore's policy settings. The manager noted that offloading the properties would mitigate the drag from the high-rate environment while redeploying capital into the trust's home market.
Macroeconomic and political stability in Singapore, coupled with the relative strength of the Singapore dollar, underpin the rationale for deepening local exposure, according to the manager. The strategic pivot aligns with Tang Organisation's broader objective of supporting higher distributions in coming years while balancing capital management needs and long-term sustainability.
Recent Performance and Sponsor Activity
Suntec REIT reported a first-half distribution per unit of S$0.03936 in July, up 24.8 per cent from S$0.03155 in the corresponding period of the prior year. Distributable income climbed 25.5 per cent to S$116.5 million, compared with S$92.8 million previously. Gross revenue for the half-year period rose 1.9 per cent to S$238.9 million from S$234.5 million.
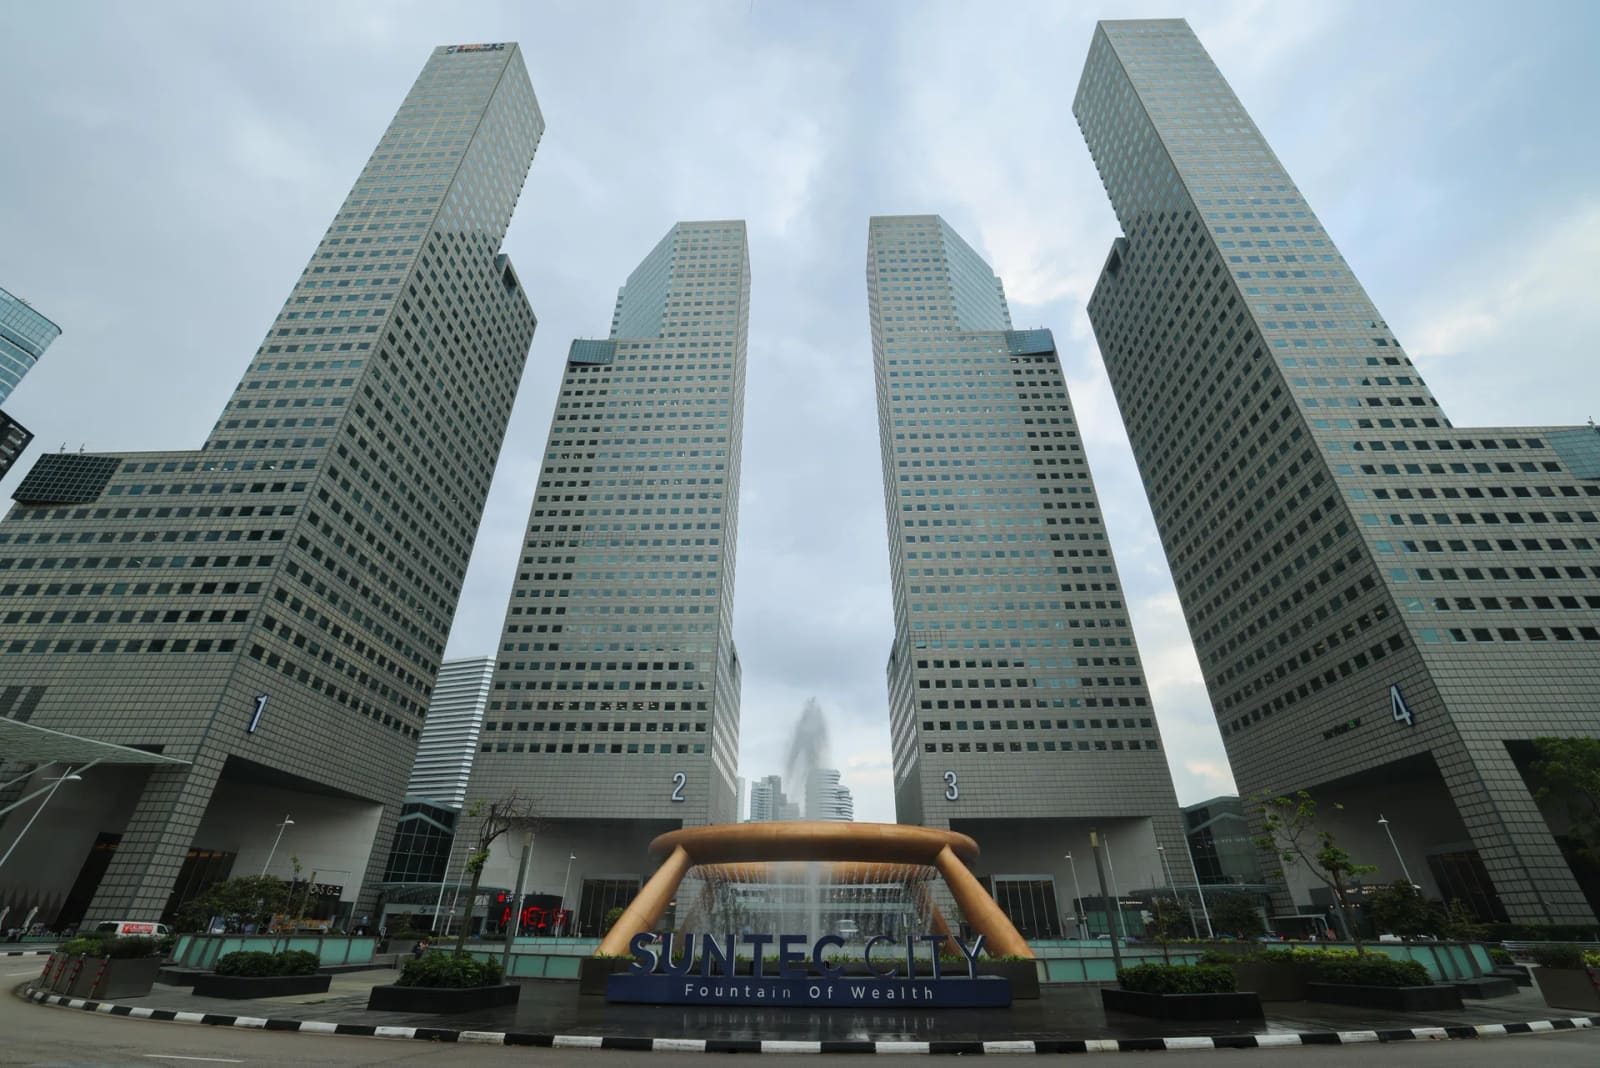
The manager attributed the improved payout to stronger operational performance in its Singapore office and retail portfolio, which includes the landmark Suntec City complex in the Marina Centre precinct. The trust has benefited from tighter vacancy rates and rental uplift in the city-state's commercial property market.
Tang Organisation's involvement has brought fresh momentum to the REIT. In a related development, Hongkong Land acquired a 10.8 per cent stake in Suntec REIT for S$541 million, signalling institutional confidence in the trust's strategic direction. Celine Tang was appointed board chairman and non-executive director as part of the ownership transition.
Capital Structure and Market Response
The planned asset sales are designed to improve the trust's capital structure at a time when investors are scrutinising leverage ratios and debt servicing capacity across the regional REIT sector. Bringing gearing below 40 per cent would position Suntec REIT comfortably within typical covenants and provide flexibility to pursue accretive opportunities in Singapore's office and retail segments.
Market participants will watch whether the trust can secure pricing that validates the manager's view on Australian capital market conditions. The three properties slated for disposal represent a modest share of total assets, but successful exits would validate the strategic pivot and potentially unlock value for unitholders.
Units of Suntec REIT closed at S$1.38 on 20 September, up S$0.01 or 0.7 per cent. The trust's yield profile and income stability remain key drivers of investor interest, particularly as the sponsor's review begins to translate into tangible portfolio changes.
The shift towards Singapore concentration marks a clear departure from earlier diversification strategies. With the divestments underway, attention turns to how the manager will redeploy the proceeds and whether additional overseas holdings will be reviewed in the UK or elsewhere.
RELATED STORIES
Singapore Capital Leads Southeast Asian Surge in Hong Kong Property Deals
Tran Quoc Bao · 3 min
Singapore REITs Raise S$4.5 Billion in Nine Months as Fundraising Momentum Extends Into 2026
Priyanka V. Rao · 3 min
Blackstone's AirTrunk Lines Up S$2 Billion Loan for Singapore REIT IPO
Anand Sundaram · 3 min

Blackstone's AirTrunk Pursues $1.6 Billion Loan Ahead of Singapore REIT Listing
Jun-ho Seo · 3 min
Spot something wrong? Email editor@briefasia.com. We log every correction publicly.