Finance · Markets
Japan's Central Bank and Markets Diverge on Rate Hike Trajectory
BOJ officials prioritise inflation control while traders brace for higher terminal rates than previously anticipated
KEY TAKEAWAYS
- ·The Bank of Japan's hawkish officials prioritise inflation control whilst market participants price in a terminal rate near 1.5 per cent by mid-2027, well above earlier forecasts.
- ·Japan's ten-year government bond yield has climbed toward 2.1 per cent, the highest in nearly three decades, as investors anticipate a prolonged tightening cycle.
- ·Rising borrowing costs pose fiscal challenges for a government with debt exceeding 250 per cent of GDP, prompting officials to explore maturity extension and retail bond incentives.
Competing Visions for Monetary Policy
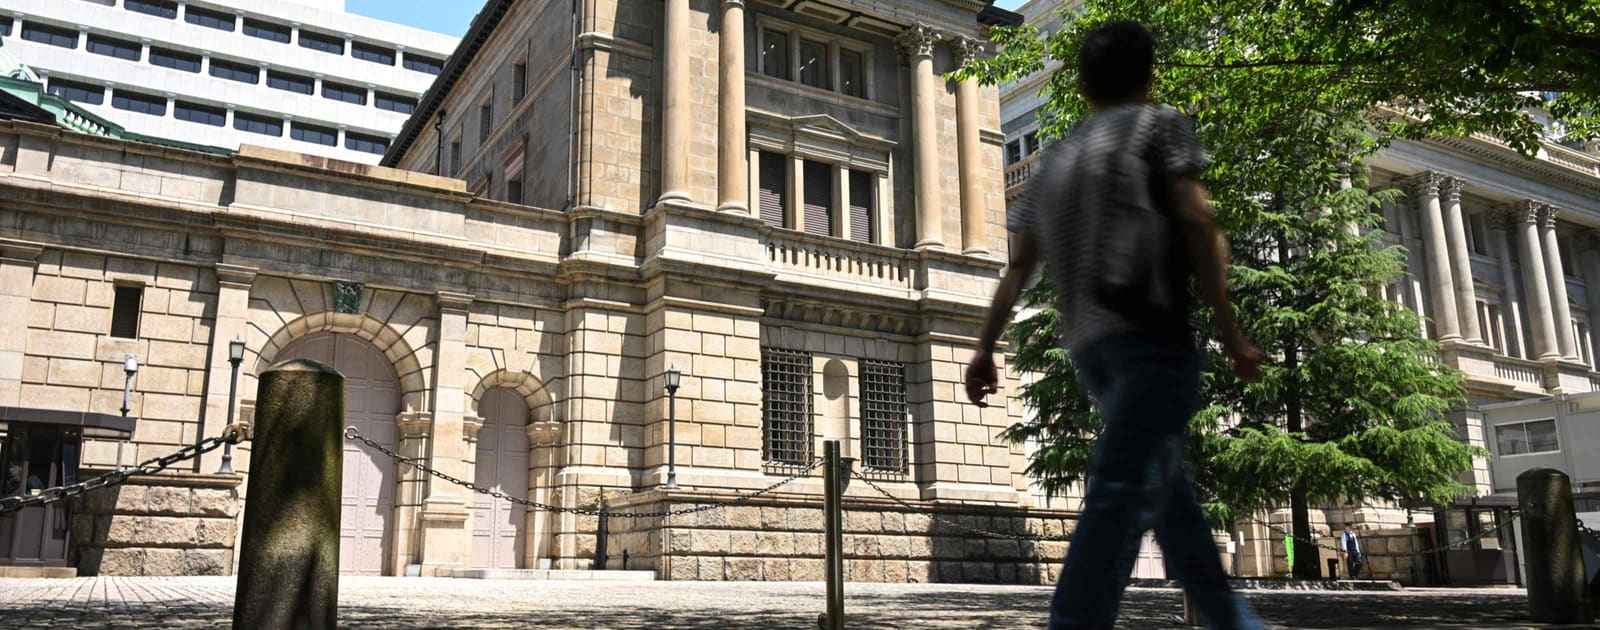
A fundamental disconnect has taken shape between the Bank of Japan's rate-setting committee and fixed-income markets over the likely path of borrowing costs. Central bank officials are emphasising the need to contain upward inflation pressure, whilst traders and portfolio managers prepare for a higher peak policy rate than earlier projections suggested.
Japan's long-dated government bond yields have climbed steadily in recent weeks, reflecting growing conviction among investors that the BOJ will need to lift rates further and faster than initially communicated. The shift marks a departure from the ultra-loose monetary stance that defined Japanese policy for more than a decade.
Inflation Concerns Drive BOJ Hawks
Several members of the BOJ's policy board have stepped up their advocacy for additional rate increases, according to people familiar with internal discussions. These officials argue that persistent inflation risks warrant pre-emptive action, even if the economy has yet to demonstrate sustained wage growth across all sectors.
The central bank's current policy rate stands at 0.75 per cent, a level reached through incremental adjustments over the past eighteen months. Market pricing now suggests a terminal rate approaching 1.5 per cent by mid-2027, significantly above the 1.0 per cent ceiling that analysts had forecast as recently as July.
Governor Kazuo Ueda has maintained that rate decisions remain data-dependent and that the BOJ will adjust policy at every meeting if conditions warrant. This open-ended commitment has fuelled speculation that the tightening cycle may prove more aggressive than the central bank's public guidance has indicated.
Market Repricing Gathers Pace
Fixed-income investors have begun repositioning portfolios in anticipation of a prolonged period of rising yields. The benchmark ten-year Japanese government bond yield has edged toward 2.1 per cent, the highest level in nearly three decades, as participants price in a sequence of quarter-point hikes extending into late 2027.
This repricing has rippled through currency and equity markets. The yen has strengthened moderately against the dollar, buoyed by expectations of a narrowing interest-rate differential with the United States. Japanese bank stocks have rallied on the prospect of improved net interest margins, whilst real-estate investment trusts have come under pressure as financing costs climb.
Foreign institutional investors, who hold roughly forty per cent of outstanding Japanese government debt, have increased their hedging activity. Derivatives markets show a sharp rise in demand for interest-rate options that pay out if yields exceed 2.5 per cent by year-end, a scenario that would mark the most dramatic shift in Japanese monetary conditions since the early 1990s.
Divergence Over Terminal Rate
The tension between the BOJ's inflation focus and market expectations centres on the question of how high rates must rise to stabilise prices without triggering a contraction. Central bank officials have emphasised that Japan's inflation dynamics differ from those in the United States and Europe, where supply-chain disruptions and energy shocks drove earlier price surges.
In Japan, inflation has been more gradual, rooted in a combination of import-cost pass-through and domestic demand recovery. This has led some BOJ board members to argue for a measured approach, with rates rising only as evidence of sustained wage-price spirals emerges.
Market participants, however, point to upward revisions in corporate pricing plans and accelerating service-sector inflation as signs that the BOJ may need to move more decisively. If inflation proves stickier than officials anticipate, the central bank could face a difficult choice between tolerating above-target price growth and imposing a sharper monetary brake.
Implications for Fiscal Policy
The shift in rate expectations carries significant consequences for Japan's public finances. The government's debt-to-GDP ratio exceeds 250 per cent, among the highest in the developed world. A sustained rise in borrowing costs would increase debt-service burdens, potentially constraining fiscal flexibility at a time when the government faces mounting social-security obligations tied to an ageing population.
Finance ministry officials have begun exploring measures to mitigate refinancing risk, including lengthening the average maturity of new issuance and considering tax incentives for retail investors who purchase government bonds. These steps reflect growing recognition that the era of near-zero interest rates has ended.
The BOJ's next policy meeting is scheduled for late September, and markets will scrutinise the accompanying statement for any adjustment to forward guidance. Whether the central bank and investors can reconcile their differing views on the pace and destination of rate hikes will shape Japan's economic trajectory through the remainder of the decade.
RELATED STORIES
Bank of Japan Signals Possible Rate Increase This Month
Aiko Nakamura · 3 min
Bank of Japan Prepares Third Rate Increase in Ten Months
Aiko Nakamura · 3 min
Bank of Japan to Continue Rate Increases to Anchor Inflation at 2 Per Cent
Aiko Nakamura · 3 min
Bank of Japan Eyes Rate Increase as Inflation Risks Mount
Cheng Wei-Lun · 4 min
Spot something wrong? Email editor@briefasia.com. We log every correction publicly.