Technology · Chips
AI Chip Complexity Pushes Substrate Supply Crunch From Materials to Equipment
Rising layer counts and larger surface areas in advanced IC substrates are exposing manufacturing capacity constraints as AI accelerator performance scales.
KEY TAKEAWAYS
- ·Advanced AI accelerators and server CPUs now require IC substrates with higher layer counts and larger surface areas due to integration of high-bandwidth memory, high-speed SerDes, and chiplet designs.
- ·The supply bottleneck has shifted from raw materials to production equipment capacity, with new substrate lines requiring twelve to eighteen months to commission and USD 80 million to USD 120 million in capital expenditure.
- ·Taiwan and South Korea control approximately 65 per cent of global IC substrate capacity, with new production lines not expected to reach volume output until late 2027 or early 2028.
Performance Race Drives Packaging Demands
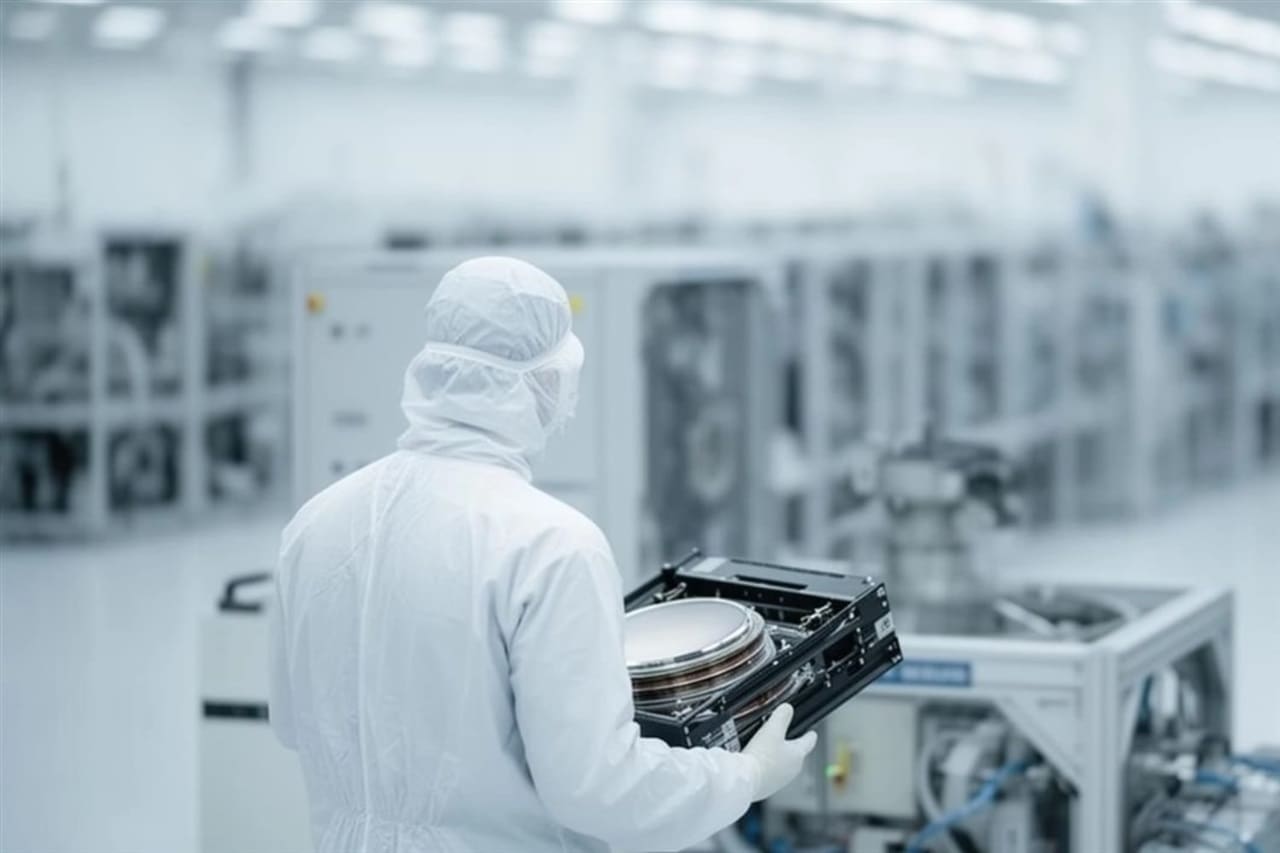
AI accelerators and server CPUs are undergoing a structural transformation that is reshaping the semiconductor supply chain in ways component suppliers did not anticipate eighteen months ago. As compute core counts climb and I/O channels multiply, the physical architecture of advanced chips is expanding both vertically and horizontally, according to industry research data.
The integration of high-bandwidth memory, high-speed SerDes interfaces, and chiplet architectures within a single package has introduced transmission, power, and interconnect challenges that legacy substrate designs cannot accommodate. High-end IC substrates now require larger surface areas and higher layer counts to support the signal integrity and thermal management these systems demand.
Equipment Capacity Emerges as Limiting Factor
The supply constraint in advanced IC substrates has migrated from upstream material availability to downstream equipment throughput. Substrate manufacturers in Taiwan, South Korea, and Japan have reported that raw material procurement for advanced substrates has stabilised over the past year, but production line capacity remains tight.
Equipment used to build multi-layer substrates with fine-pitch vias and complex trace routing operates at significantly lower throughput than machinery designed for conventional substrates. A single production line for substrates exceeding twenty layers can take twelve to eighteen months to commission, and capital expenditure per line ranges from USD 80 million to USD 120 million depending on process capability.
Leading substrate suppliers including Ibiden, Unimicron, and Nan Ya PCB have announced capacity expansion plans, but new lines are not expected to reach volume production until late 2027 or early 2028. In the interim, allocation of advanced substrate capacity is determined by long-term supply agreements, leaving smaller chip designers and fabless firms competing for spot availability.
Asia Supply Chain Adjusts to New Reality
Taiwan and South Korea account for approximately 65 per cent of global IC substrate production capacity, with Japan holding another 20 per cent. The concentration of substrate manufacturing in Northeast Asia has accelerated collaboration between equipment makers and substrate producers to optimise line utilisation.
Japanese equipment manufacturers including Tokyo Electron and Shibaura Mechatronics have introduced automated inspection and layer alignment systems designed to reduce cycle time and improve yield on high-layer-count substrates. These systems are being deployed in pilot lines across Taiwan and South Korea, with production rollout scheduled for the first half of 2027.
Substrate material suppliers in Asia have shifted focus from capacity expansion to process development. Companies in Taiwan and Japan are working on dielectric materials with lower signal loss and copper foils with improved adhesion properties to support substrates exceeding thirty layers, a threshold that several next-generation AI accelerators are expected to require by 2028.
Implications for Chip Supply and Pricing
The equipment bottleneck in advanced substrate production is creating allocation pressure across the AI chip ecosystem. Hyperscale cloud providers and enterprise server manufacturers with committed substrate capacity are securing stable supply, while smaller AI chip startups face lead times exceeding six months for prototype runs.
Substrate pricing for advanced packages has risen approximately 15 to 20 per cent over the past twelve months, reflecting both equipment amortisation costs and tight allocation. Chip designers are responding by optimising die size and I/O configurations to reduce substrate layer count where possible, though this approach carries trade-offs in performance and power efficiency.
The substrate equipment constraint is unlikely to ease materially before 2028, barring a slowdown in AI chip performance scaling. Equipment lead times remain extended, and substrate manufacturers are prioritising capacity commitments to customers with multi-year volume agreements. For the broader semiconductor supply chain, the lesson is familiar but no less consequential: performance advances at the chip level cascade through the entire ecosystem, often exposing bottlenecks in places the industry least expects.
RELATED STORIES
Taiwan Indicts Nvidia Manager in Chip-Smuggling Investigation
Cheng Wei-Lun · 4 min
Fujifilm Triples Wafer Cleaner Capacity as AI Chip Demand Surges
Cheng Wei-Lun · 3 min
Asia's AI Chip Startups Face Manufacturing Reality Check
Priyanka V. Rao · 4 min
Intel's Gelsinger Dismisses HBM as 'Lousy' While SK Hynix Signals Search for Successor
Cheng Wei-Lun · 3 min
Spot something wrong? Email editor@briefasia.com. We log every correction publicly.