Technology · Dev
Southeast Asia's Data Centre Rush Faces Power Grid Reality
Rapid infrastructure expansion meets transmission constraints, raising questions about whether the region can build a coordinated AI ecosystem beyond national boundaries
KEY TAKEAWAYS
- ·Southeast Asia accounts for roughly 13 GW of the Asia-Pacific's 26.5 GW data centre development pipeline recorded in the first half of 2026, with Malaysia leading at 1,039 MW and Thailand at 859 MW.
- ·Thailand froze approvals for about 117 projects in early September until national rules on power, water, and siting are finalised, while Malaysia's Johor state faces water supply and grid connection constraints.
- ·ASEAN's Digital Economy Framework Agreement, signed in November 2026, aims to reduce regulatory friction across cross-border data flows, cybersecurity, and talent mobility ahead of Singapore's 2027 chairmanship.
Capacity Surge Meets Infrastructure Limits
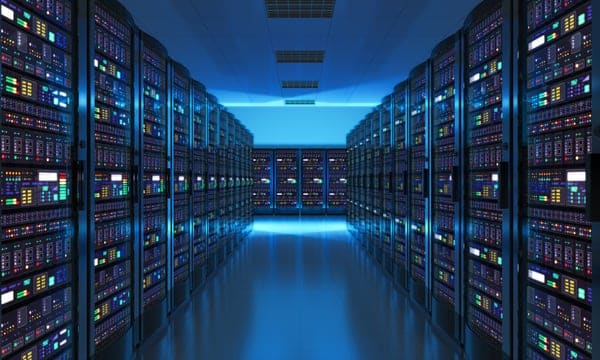
Asia-Pacific recorded 26.5 GW in its data centre development pipeline during the first half of 2026, with Southeast Asia accounting for approximately half the construction activity. Malaysia's pipeline stands at 1,039 MW, Thailand's at 859 MW, according to industry data.
Yet construction figures diverge sharply from operational reality. Singapore operates 1.46 GW, the region's largest live base, but faces tight restrictions on new approvals. The government's second Data Centre Call for Applications awarded just 200 MW to four operators from over 20 applicants on 21 August. Plans for a low-carbon park on Jurong Island signal a continued focus on premium workloads rather than volume expansion.
The city-state's constraints stem from limited power availability, land scarcity, and sustainability mandates. These factors push Singapore toward high-value compute segments, including research and specialised workloads, while steering hyperscale projects across the Johor Strait.
Diverging National Strategies
Malaysia has captured the bulk of scale-oriented investment, leveraging available land and lower costs. Thailand had been expanding rapidly from a smaller baseline, with investment approvals and partnerships with domestic utilities driving growth near Bangkok.
Indonesia pairs a 288 million-person domestic market with foreign AI capital. CoreWeave's planned 360 MW deployment in Greater Jakarta illustrates the shift from serving local demand to becoming a destination for international AI infrastructure. The country mandates that government and designated strategic data remain onshore.
Vietnam, with 102 million residents, opened its market by permitting wholly foreign-owned data centres. The regulatory liberalisation aims to attract capital while building domestic digital capacity.
Cross-Border Coordination Emerges
On 1 August, SoftBank's Singapore subsidiary signed a memorandum of understanding with SC ZEUS, a Singapore-based developer, and Robust HPC, a Malaysian high-performance computing specialist. The agreement targets AI data centre capacity in Malaysia, Thailand, Indonesia, and Vietnam.
Investors increasingly treat ASEAN markets as complementary sites within a single infrastructure strategy rather than isolated opportunities. Capital flows reflect this logic, with constraints in one country influencing deployment decisions in neighbours.
Yet redistributing investment across borders does not eliminate physical bottlenecks. In early September, Thailand asked developers to pause work on roughly 49 projects under construction and froze approvals for about 117 until national rules on power, water, siting, and local benefit are finalised. Malaysia's Johor state, which borders Singapore, faces water supply pressure alongside grid connection delays.
Transmission capacity and the speed of new power delivery now constrain both Bangkok and Kuala Lumpur. The United States, which holds around 45 per cent of global data centre capacity, confronts similar grid connection challenges as demand outpaces supply.
Regional Grids and Economic Capture
The ASEAN Power Grid seeks to enable cross-border electricity trade. The Laos-Thailand-Malaysia-Singapore Power Integration Project offers an early model. Greater regional power connectivity will not eliminate local shortages, but it expands the geography over which supply and demand can be balanced.
A parallel question concerns economic value. Data centres deliver construction activity, engineering employment, energy investment, and tax revenue. Yet much of the higher-value work associated with AI resides in software, model development, research, and specialised services.
Hosting computing capacity without developing a corresponding AI economy mirrors the experience of countries with large electronics assembly operations that lack design, chip production, or software layers. Governments can use access to land, power, and incentives to secure commitments on skills development, research partnerships, supplier programmes, and domestic firm access to computing resources.
Regulatory Fragmentation Risk
While infrastructure spreads geographically, governance remains national. A company placing servers across ASEAN countries must navigate distinct requirements for data governance, cybersecurity, licensing, and cross-border digital services in each market.
Fragmentation could outpace regulatory coordination. The region might accumulate computing capacity without capturing the economic advantages of regional scale, with facilities serving only national markets and firms duplicating functions across jurisdictions.
ASEAN's Digital Economy Framework Agreement, signed in November 2026, addresses cross-border data flows, electronic payments, data protection, talent mobility, AI, and cybersecurity. The agreement cannot integrate physical infrastructure or determine data centre licensing, but it can reduce regulatory friction that makes regional digital operations costly.
Singapore assumes the 2027 ASEAN chairmanship two months after DEFA's signing. The timing presents an opportunity to advance both formal adoption and practical implementation.
Beyond Gigawatts
National ambitions for control over AI and data will persist. Regional integration need not require governments to surrender oversight of sensitive infrastructure. Instead, common rules and interoperability allow countries to retain control while capturing economies of regional scale.
The objective is converting infrastructure investment into skills, research capacity, local suppliers, and broader AI adoption. A company operating in one country, computing capacity in another, and electricity from a wider regional grid need not function as entirely separate national systems.
Construction figures make compelling headlines, but the meaningful measure is what the infrastructure enables next. Deploying facilities across multiple countries presents one challenge. Making national systems function together at a regional level demands coordination among governments, investors, and ASEAN institutions to ensure projects complement rather than duplicate one another.
RELATED STORIES
Southeast Asian Firms Overlook Digital Pact Worth USD 2 Trillion
Lim Hui Ying · 4 min
Five ASEAN Members Back Regional Oil Stockpile as Study Nears Completion
Tran Quoc Bao · 3 min
Indonesian Digital Banks Outpace Regional Peers on Deposits and Loan Growth
Priyanka V. Rao · 3 min
Laos Hydropower Faces Solar and Wind Competition as Regional Grid Expands
Tran Quoc Bao · 4 min
Spot something wrong? Email editor@briefasia.com. We log every correction publicly.